🏭 Applied Materials Just Printed a Record. So Why Is $AMAT Bleeding? 📉🔥
Applied Materials ($AMAT) just booked a record $10.41 billion quarter and told Wall Street that 2027 will be bigger still. The stock has dropped about 8% since. A guidance number that beat one scoreboard and missed another, plus a supply chain that can’t keep up, explains the disconnect.


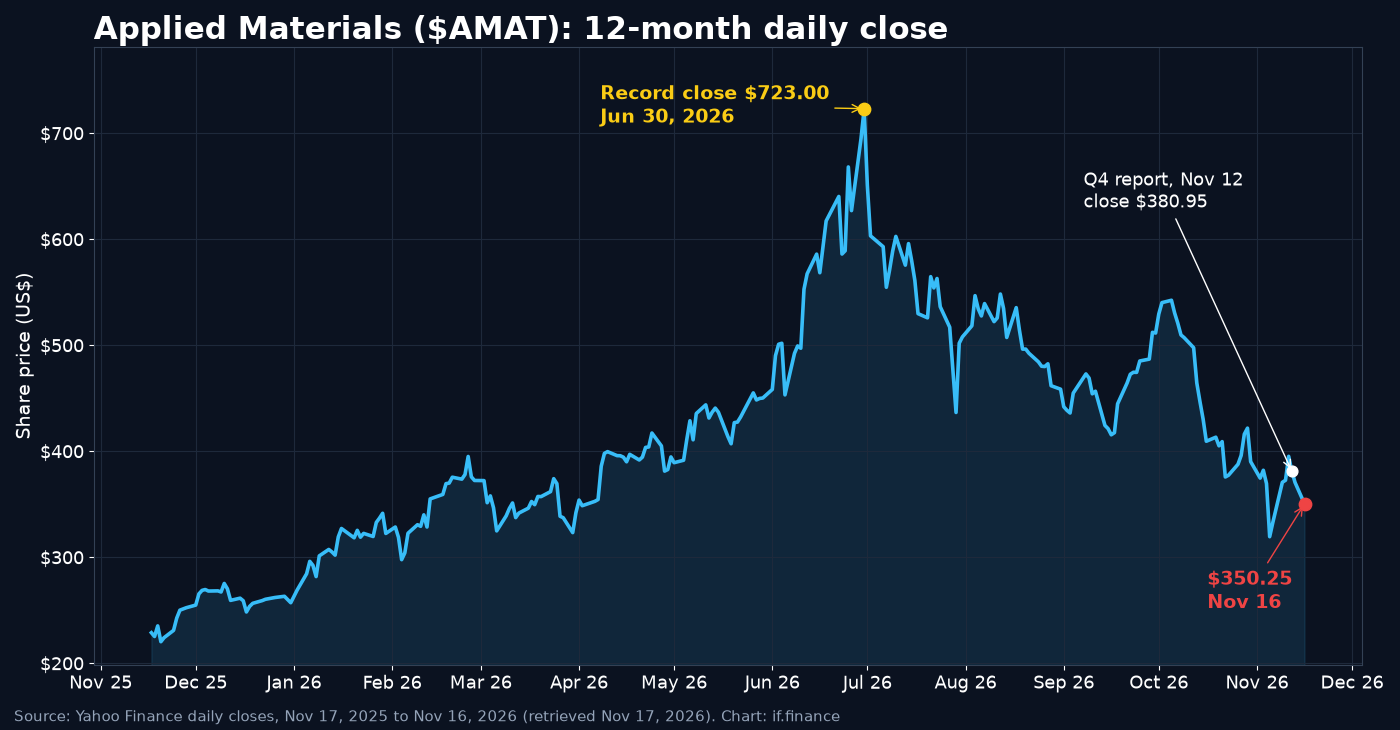
Applied Materials stock should be throwing a party. The chip-equipment giant grew sales 53% in its fiscal fourth quarter, nearly doubled adjusted profit per share, and its CEO is calling for another record year. [1][5] Instead, $AMAT closed Monday at $350.25, about 8% below its pre-report close and less than half its June 30 record close of $723.00. [6]
Applied sells the equipment chipmakers use to build and inspect advanced chips, and it sits on Grok’s stock picks list. So why did its best quarter ever land with a thud?
Applied doesn’t make chips; it makes the deposition, etch and inspection machines the world’s biggest chipmakers depend on. Its two largest customers are Taiwan Semiconductor Manufacturing Co. (TSMC), which builds chips for Nvidia and Apple, and Samsung Electronics, a giant in memory. In fiscal 2024, the last year Applied named them, Samsung was 12% of revenue and TSMC 11%. [7] Applied stopped naming them in fiscal 2025 but said two customers made up about 19% and 15% of sales, roughly a third of the business. [8]
The record nobody wanted to celebrate
Nobody celebrated because investors looked past the record to the next quarter: Applied’s $11.1 billion revenue forecast missed the higher Wall Street estimates, even though it covers an extra week, and the CFO admitted supply shortages were holding sales back.
For the quarter ended Oct. 25, revenue rose 53% to $10.41 billion from $6.80 billion a year earlier. GAAP earnings per share (the standard accounting measure) rose 43% to $3.40. Non-GAAP EPS, which strips out items such as acquisition charges and certain tax effects, jumped 92% to a record $4.16. Non-GAAP gross margin reached 50.6%, and non-GAAP operating margin widened to 35.3% from 28.6%. [1]
Analysts polled by LSEG had expected adjusted EPS of $4.05. [3] Full-year revenue climbed 21% to a record $34.45 billion, Applied’s seventh straight year of growth. [1][5]
Applied also bought back $2.00 billion of stock, its largest quarterly buyback in more than eight years per CFO Brice Hill, and paid $421 million in dividends. [1]
Beat or miss? Depends on whose scoreboard
The selling traces back to one number: first-quarter revenue guidance of $11.1 billion, plus or minus $500 million. Against the $10.89 billion LSEG average cited by Reuters, that is a beat. [3] Against the $11.41 billion consensus cited by Yahoo Finance, it is a miss, and it covers a 14-week quarter, one week longer than usual. [4][5] The $4.35 EPS guide topped the $4.25 consensus in that same report. [1][4]
Hill blamed supply, not demand:
“Our Q1 number would be slightly higher if everything were perfectly available.” Brice Hill, CFO [5]
Wall Street trimmed anyway. At least 10 firms cut targets, Summit Insights downgraded the stock to Hold, and Jefferies cut its target to $580 from $770 while keeping a Buy rating. Morningstar went the other way, lifting its fair value estimate to $570 from $520 and calling AI concerns “overblown at this point.” [4]
$AMAT closed at $380.95 on report day, was down about 6% by late Friday morning, closed Friday at $370.50 and fell another 5.5% Monday to $350.25. [4][6]
Where the money is coming from
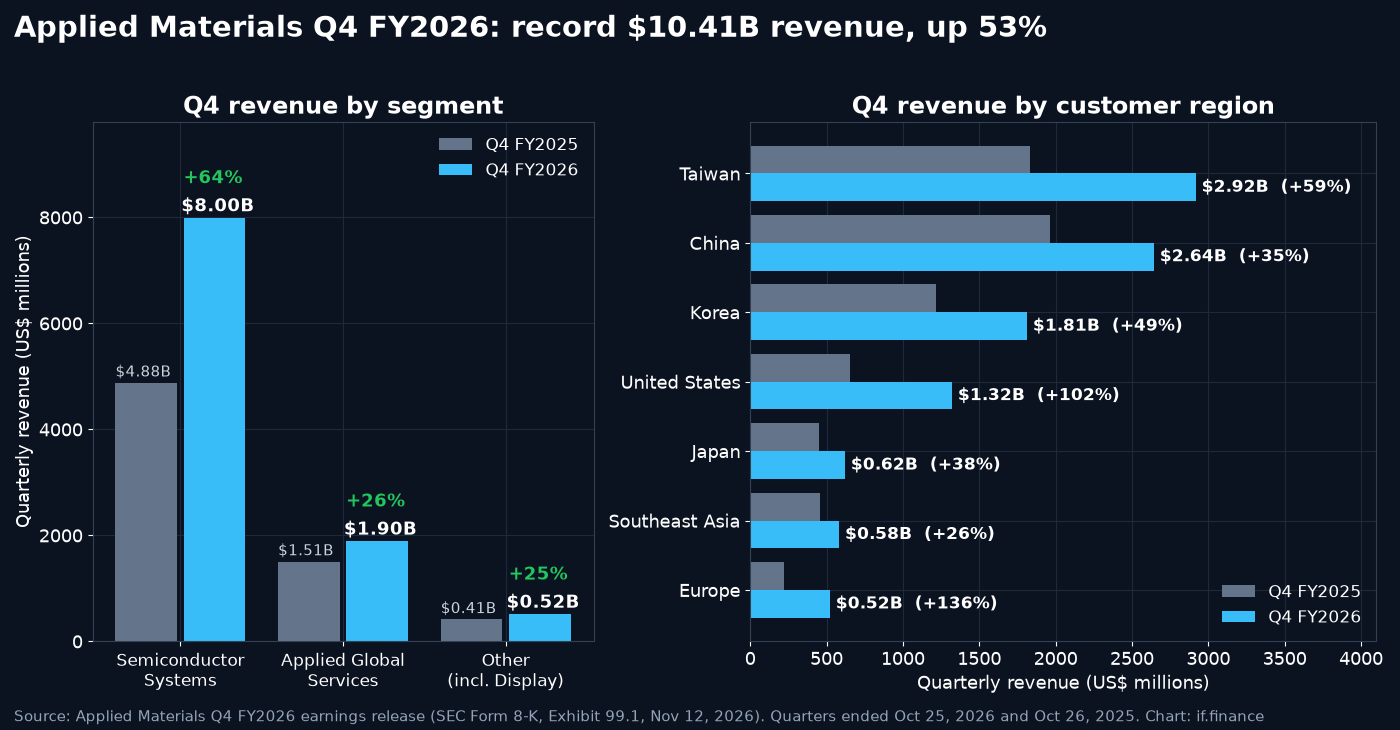
Semiconductor Systems, the equipment business, did the heavy lifting. Revenue jumped 64% to $8.00 billion, with a 38.8% operating margin. Memory was the engine: DRAM rose to 33% of systems sales from 28% a year earlier and flash memory to 9% from 6%, while foundry and logic slipped to 58% from 66%. Applied Global Services, the parts and service arm, grew 26% to $1.90 billion. [1] Management expects advanced packaging revenue to rise about 90% this calendar year and inspection and metrology more than 50%. [5]
Memory is the same corner of the AI trade where we watched Micron get mugged by Kioxia’s warning, except Applied gets paid whenever memory makers add capacity.
By customer region, Taiwan was the largest at $2.92 billion, or 28% of revenue. China sales grew about 35% to $2.64 billion but fell to 25% of the total from 29%. [1][3] Management expects China to be less than 25% of the business in 2027. [5] U.S. revenue roughly doubled to $1.32 billion. [1] Taiwan is home base for TSMC and Korea for Samsung, so those two customers’ spending plans move Applied’s numbers more than anyone’s.
Applied Materials stock and the capacity bet
“We expect 2027 to be another record year for the market and for Applied.” Gary Dickerson, CEO [5]
He expects wafer fab equipment (WFE) spending, the industry’s total budget for chipmaking tools, to rise more than 30% next year, and said Applied’s largest customers now give it rolling eight-quarter forecasts and earlier orders. [5] Hill said clean room capacity “remains a gating factor” for how much equipment the industry can absorb. [5] Applied is investing to double its systems output from fourth-quarter levels by 2028 and more than double its manufacturing and lab capacity by 2030. [5]
It is also locking in partners. In October, Applied agreed to raise its stake in Amsterdam-listed packaging-equipment maker BE Semiconductor Industries (Besi) to about 20%, pending the U.S. antitrust waiting period, to push hybrid bonding and new chip-stacking and interconnect methods. [2] Its new EPIC Center R&D hub in Silicon Valley signed Intel as a founding partner, with Kioxia and Besi as innovation partners. [1] Closer to home for Texas readers, Reuters notes Applied is a partner in Apple’s American Manufacturing Program, which includes work at Applied’s Austin facility to boost U.S. production of chipmaking equipment. [3]
Our Take
We think the market is punishing Applied for being sold out. A company that would ship more if parts showed up does not have a demand problem. It has a fixable scheduling problem.
The scoreboard fight is noise. One consensus says beat, another says miss, and the gap is about $310 million in a 14-week quarter. If your thesis hinges on that, you need a nap, not a trade.
The valuation is no longer heroic. Going into Friday, Applied traded at about 22 times forward earnings, near its 21x five-year average and less than half its 49x peak in June. [4] We like this stock a lot more at $350 than we did at $723, which is the kind of sentence that ages either beautifully or terribly.
Our real worry is the capacity race. Doubling output by 2028 is a bet that the AI building boom keeps running. If it stalls, those new lines become shiny paperweights.
Bull case vs. the risks
The bull case:
- WFE spending is expected to rise more than 30% in 2027, and Applied says it is positioned to outgrow the market. [5]
- Demand exceeds supply. TECHnalysis Research analyst Bob O’Donnell told Reuters chipmakers are “buying as much equipment as they possibly can.” [3]
- Applied expects to return 80% to 100% of free cash flow to shareholders over time. [5]
The risks:
- Parts and clean room shortages could cap shipments however strong orders are. [5]
- China is still a quarter of revenue, and Applied flags export rules, licenses and tariffs among its risks. [1]
- New capacity would sit idle if AI spending cools. [4]
- Volatility: the stock went from $228.71 a year ago to $723.00 in June, then closed at $319.25 on Nov. 5. [6]
What to watch next
- Output. Hill expects output to rise every quarter this year. [5]
- ASML’s Jan. 27 report. The next read on whether equipment supply can catch demand. [4]
- The Besi stake. Share delivery waits on the U.S. antitrust waiting period. [2]
- China mix. Management expects China below 25% of revenue in 2027. [5]
- The next guide. Applied’s fiscal first-quarter report will show whether supply is still the only brake. [4] Follow more chip stocks in our Technology Picks section.
Bottom line: Applied Materials just proved AI chip demand is real; now it has to prove it can build the machines fast enough to cash in.
This article is for information only and is not investment advice.
References
- Applied Materials Announces Fourth Quarter and Fiscal Year 2026 Results (Form 8-K, Exhibit 99.1), Applied Materials, Inc. via SEC EDGAR, November 12, 2026.
- Applied Materials to Increase its Strategic Investment in BE Semiconductor Industries (Form 8-K, Exhibit 99.1), Applied Materials, Inc. via SEC EDGAR, October 26, 2026.
- Applied Materials forecasts quarterly revenue above estimates on strong AI chip demand, Reuters (Prathik Jayaprakash) via Investing.com, November 12, 2026.
- Applied Materials Sinks 6% After Record Quarter as 10 Analysts Cut Targets; Morningstar Calls AI Worries “Overblown”, Yahoo Finance (Chris Arnold), November 13, 2026.
- Applied (AMAT) Q4 2026 Earnings Call Transcript, The Motley Fool, November 13, 2026 (call held November 12, 2026).
- Applied Materials, Inc. (AMAT) Stock Historical Prices & Data, Yahoo Finance, daily closes retrieved November 17, 2026.
- Applied Materials Form 10-K, fiscal 2024 (SEC)
- Applied Materials Form 10-K, fiscal 2025 (SEC)
Image credits
- Featured image: base photo “Sitz von Applied Materials in Santa Clara” (shows the Maydan Technology Center sign) by Olaf2, Wikimedia Commons, CC BY-SA 4.0. Cropped, adjusted and overlaid with text and data by if.finance; the derivative is shared under the same license.
- Logo: Applied Materials logo, Wikimedia Commons, public domain (PD-textlogo). Trademark of Applied Materials, Inc., used for identification only.
- Price chart: made by if.finance from Yahoo Finance daily closing prices.
- Segment and region chart: made by if.finance from the Applied Materials Q4 FY2026 earnings release filed with the SEC.