Vertiv ($VRT) Just Doubled Its Orders. So Why Is the Stock Still Nearly 40% Off Its High?
Organic orders more than doubled. Sales jumped 61% to $4.3 billion. Full-year guidance went up by $650 million. And even after a 14% one-day pop, the stock was still nearly 40% below its May record. Our take: Vertiv is the AI trade’s plumber, the market still hasn’t settled on what that’s worth, and the next leg depends on whether orders stay this hot.

Vertiv Holdings Co ($VRT) doesn’t make the AI chips that grab the headlines. It makes the things those chips can’t run without: power systems, liquid and air cooling, racks, and the service crews behind them. Unglamorous? Sure. But when Vertiv reported third-quarter results on October 28, it showed that the picks-and-shovels side of AI is growing faster than almost anyone on Wall Street expected. Net sales rose 61% from a year earlier to $4.313 billion, and organic orders (excluding acquisitions and currency moves) grew more than 100%. [1]
Vertiv is one of the AI-infrastructure names on Grok’s October stock-picks list. Our view: this quarter was the clearest evidence yet that the AI build-out is still speeding up where it physically counts. Here’s what the numbers say and where the trap could be.
A blowout on every line
GAAP diluted earnings per share jumped 91% to $1.95. Adjusted EPS, which strips out items such as acquisition-related amortization, rose 78% to $2.21. Net income nearly doubled to $764.5 million from $398.5 million. [1][2]
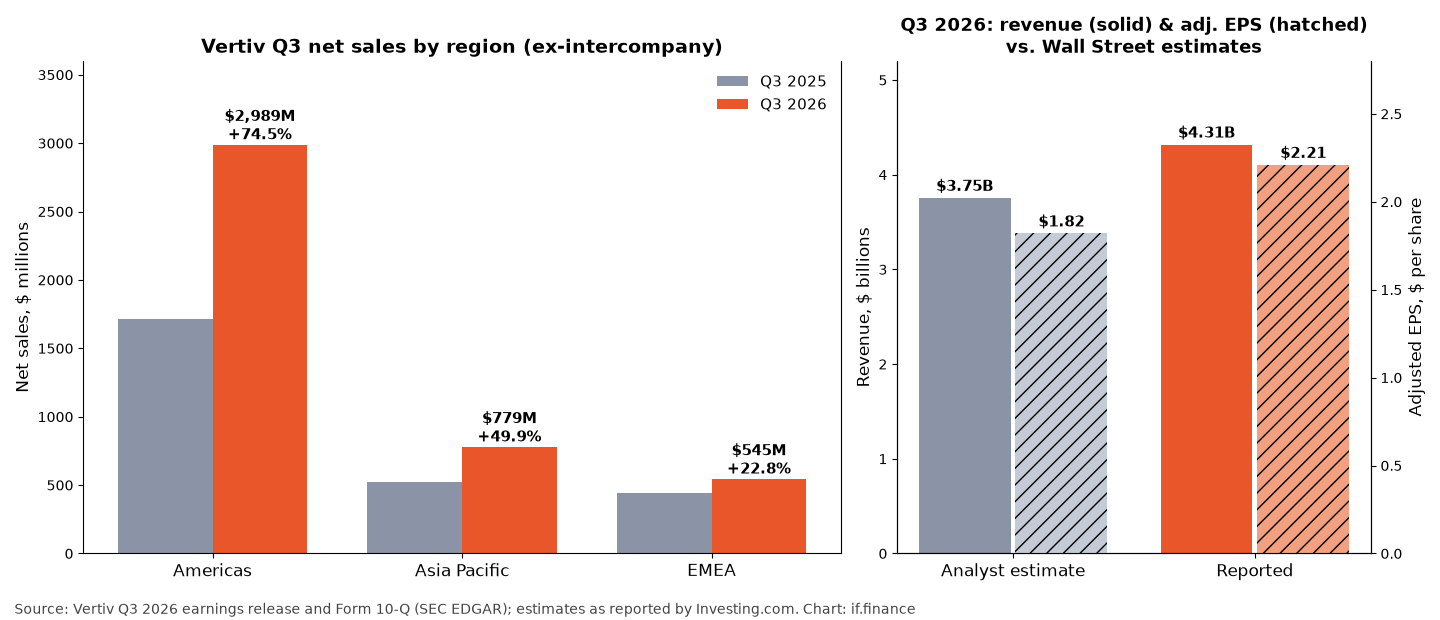
Analysts had expected about $1.82 a share of adjusted earnings on $3.75 billion of revenue, according to Investing.com. [4] Investopedia, using Visible Alpha estimates, also said both figures came in well above forecasts. [3] This wasn’t a squeaker. It was a rout of expectations.
Profitability scaled with it. Adjusted operating profit rose 83% to $1.087 billion, and the adjusted operating margin widened 2.9 percentage points to 25.2%. Operating cash flow was $794 million, adjusted free cash flow was $652 million, liquidity reached $6.2 billion, and Vertiv says it now holds more cash than debt. [1]
Our take: margins expanding while sales grow 61% is the tell. That’s pricing power, not just volume, and it’s the strongest argument that this is more than a sugar high.
America is where the AI money is landing
The Americas, Vertiv’s largest segment, grew net sales 74.5% to $2.99 billion at a 29.4% operating margin. Asia Pacific rose 49.9% to $779 million, with its margin up to 17.0% from 13.2%. EMEA was the laggard, up 22.8% to $545 million, but its margin jumped to 28.0% from 18.8%. [2]
About 6 points of the 61% growth came from acquisitions, including PurgeRite, which Vertiv bought for about $1.14 billion net of cash in a deal that closed in December 2025. [1][2] Deals like that add service work around the gear Vertiv already sells, and that work matters more as AI racks run hotter and need more cooling.
CEO Giordano Albertazzi didn’t hedge: “We are in the middle of the largest infrastructure buildout and it’s accelerating.” [1] He said Vertiv is shortening product development “from years to months” and building more prefabricated, “converged” systems that combine power and cooling in one package. [1]

Management just raised the bar on itself
Vertiv raised full-year guidance across every key metric. It now expects 2026 net sales of $14.45 billion to $14.85 billion, $650 million more than before at the midpoint, with organic growth of 37% to 39%. Adjusted EPS is now guided to $7.10 to $7.20, up 69% to 71%, with adjusted free cash flow of $2.6 billion to $2.8 billion. [1]
For the December quarter, the company guided to net sales of $4.313 billion to $4.513 billion and adjusted EPS of $2.22 to $2.28. Investopedia reported that both midpoints topped consensus. [1][3] Capital spending is still planned at about 4% of revenue as Vertiv adds factory capacity. [1]
The 40% question
The market cheered. Shares rose about 13% in premarket trading on October 28 from a $208.56 prior close, and they were up 14% later in the session, leading the S&P 500. [3][4] But here’s the tension: even after that jump, Investopedia noted the stock was up 45% for the year and still nearly 40% below its May record high. [3] You can follow the price on our live chart page.
Think about that. Orders more than doubled, margins rose, and guidance went up, yet the stock sat far below where buyers paid up just months earlier. Management says the backlog still covers roughly 12 to 18 months of work, and Albertazzi stressed that Vertiv counts only firm purchase orders, “not a capacity agreement.” [4]
Our take: that gap is either the market’s biggest blind spot in AI infrastructure or a warning that investors don’t trust how long this lasts. We lean toward blind spot, but the bear case deserves real respect.
The bear case: when the giants blink
Vertiv’s growth leans on a small group of very large data-center builders. If hyperscalers (the giant cloud companies) slow their AI spending, orders can fall fast. Vertiv’s own 10-Q lists the risk of failing to realize sales expected from its backlog and of customers cancelling orders. [2] Tariffs are another unknown: the filing says any refunds of tariffs the Supreme Court struck down in February 2026 are uncertain and may not equal what was paid. [2] And a stock that went from a May record to a roughly 40% drawdown has already shown how fast sentiment can flip.
What to watch next
- Fourth-quarter delivery. Can Vertiv hit its $4.41 billion sales midpoint and a 25.3% to 26.3% adjusted margin? [1]
- Order momentum. More than 100% organic order growth is hard to repeat. A sharp slowdown would matter more than a small revenue miss.
- Hyperscaler budgets. AI spending plans at the largest cloud companies drive demand for power and cooling gear.
- Liquid cooling and services. Watch how fast acquired businesses and converged systems add to recurring service revenue.
- More AI infrastructure coverage in our AI and Super Intelligence section.
The bottom line (opinion): $VRT just proved the AI build-out is still accelerating in physical power and cooling. The stock’s discount to its May high says the market isn’t convinced. If orders stay hot, that discount looks like an opportunity. If they cool, it was a warning.
This article is for information only and is not investment advice. Sections marked “Our take,” “Our view” or “opinion” are if.finance analysis and opinion. Figures are from company filings and the reporting cited below as of November 2, 2026.
References
- Vertiv Reports Strong Third Quarter 2026 with Net Sales Growth of 61%, Organic Orders Growth over 100% and Diluted EPS Growth of 91%; Raises Full Year 2026 Guidance, Vertiv Holdings Co (press release; also filed as Exhibit 99.1 on SEC EDGAR), October 28, 2026.
- Vertiv Holdings Co Form 10-Q for the quarter ended September 30, 2026, U.S. Securities and Exchange Commission (EDGAR), filed October 2026.
- Nvidia Partner Vertiv Leads S&P 500 Gainers After Strong Earnings, Raised Outlook, Investopedia (Aaron McDade), October 28, 2026.
- Earnings call transcript: Vertiv tops Q3 2026 estimates and raises outlook, Investing.com, October 28, 2026.
Image credits
- Featured graphic: made by if.finance using “Datacenter Server Racks” by Carl Lender (Wikimedia Commons, from Flickr, CC BY 2.0). The photo was cropped and darkened, with text and figures added. The figures come from Vertiv’s Q3 2026 earnings release and Investopedia.
- Featured photo (in article): “Datacenter Server Racks” by Carl Lender, Wikimedia Commons (from Flickr), licensed CC BY 2.0. Cropped to 1200×628 by if.finance.
- Vertiv logo: from vertiv.com (site header file Vertiv-Logo.svg, converted to PNG). Trademark of Vertiv Holdings Co, shown for identification only.
- Vertiv OneCore: “Vertiv OneCore” by Vertiv, Wikimedia Commons, released under CC0 1.0.
- Chart: made by if.finance from Vertiv’s Q3 2026 earnings release and Form 10-Q, with estimates reported by Investing.com.