🚀 AMD’s Record AI Quarter Just Torched the Bubble Scare 🔥📈
Wall Street spent the last few sessions pricing an AI hangover. Advanced Micro Devices ($AMD) just dropped a record quarter that says the hangover can wait. Data-center revenue nearly doubled, the fourth-quarter guide cleared consensus, and the stock ripped higher before the open.


$AMD sits on Grok’s stock picks for a reason. Opinion: this was not a polite beat — it was a flare shot at traders who treated last week’s Intel dump as an AI-demand funeral.
The scare met a $13.4 billion brick wall
AMD reported third-quarter revenue of $13.4 billion ($13,377 million), up 45% from $9.25 billion a year earlier, with GAAP diluted EPS of $1.46 and non-GAAP diluted EPS of $2.09. Non-GAAP gross margin was 56%; non-GAAP operating income hit $3.9 billion. [1]
Versus Wall Street, that cleared the bar. LSEG consensus expected about $13.09 billion in revenue and $1.95 in adjusted EPS, per CNBC and Reuters. [2][3] After the print, shares jumped about 8% in extended trading Tuesday, then about 7.3% in Wednesday premarket, according to CNBC and Reuters. [2][4]
CEO Lisa Su did not sound like someone managing a bubble exit:
“We delivered a record quarter with revenue exceeding the high end of our guidance as Data Center segment sales nearly doubled year-over-year… we expect growth to accelerate further in the fourth quarter as we scale Helios and ‘Venice’ production.” [1]
CFO Jean Hu framed the operating leverage bluntly: revenue up 45%, non-GAAP EPS up 74%. [1]
Data Center is no longer a segment. It’s the company.
The chart that matters is not “nice AI growth.” It’s capture.
- Data Center: a record $8.5 billion ($8,546 million), up 97% year over year, on EPYC CPUs and Instinct MI450 Series GPUs. [1]
- That unit was 64% of revenue, up from 47% a year ago. [2]
- Client and Gaming: $3.7 billion, down 8% (Client $2.9B, +7%; Gaming $773M, -40%). [1]
- Embedded: $1.1 billion, up 29%. [1]
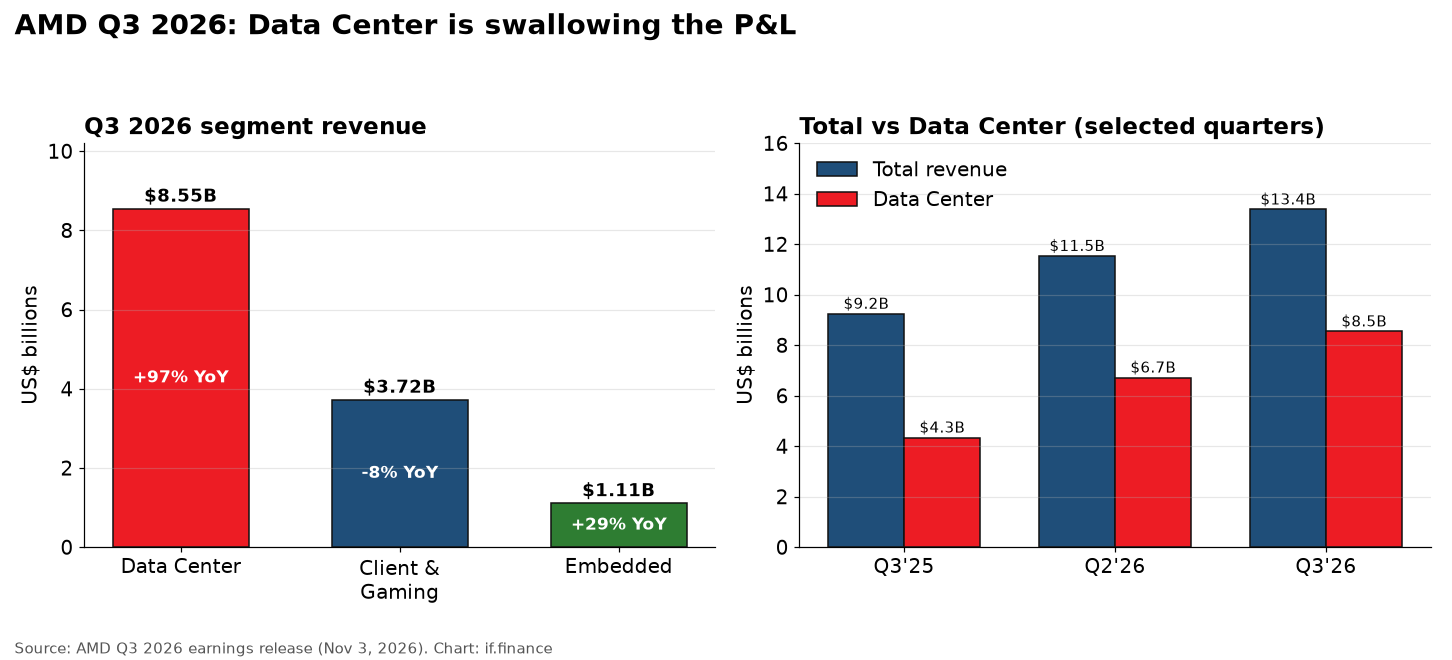
Reuters put the beat in street terms: about $8.55 billion versus estimates near $8.20 billion. [3] Opinion: when nearly two-thirds of the P&L is AI silicon and that slice is nearly doubling, the PC cycle becomes a side quest.
Hyperscalers are already on the new stack. AMD says Anthropic, Meta, Microsoft, OpenAI and Oracle Cloud Infrastructure are running workloads on the first Helios racks — Instinct MI450 GPUs plus 6th Gen EPYC. [1]
Guidance that punched the AI-spend panic in the mouth
For Q4 2026, AMD guided revenue to about $17 billion, plus or minus 3% — roughly 66% year over year and about 27% sequentially at the midpoint — with non-GAAP gross margin near 55%. [1] Reuters said that midpoint cleared LSEG’s roughly $16.23 billion consensus. [3]
The bigger tell was 2027. On the call, Su said AMD expects overall revenue to rise more than 80% in 2027 — ahead of the about 77% analysts were modeling, per LSEG via Reuters — and that data-center chips would be about 80% of sales and “drive the majority of our revenue and earnings growth.” [3][4] CNBC separately reported her view that server revenue doubles year over year in 2027 and that data-center AI growth is accelerating even faster than AMD projected 90 days earlier. [2]
“We have worked across our supply chain to secure the wafers, substrates, advanced packaging, memory, and other key components needed to support much higher growth next year,” Su said. [2]
Opinion, clearly labeled: that is not the cadence of a company whispering “maybe CapEx cools.” That is a CEO telling investors the bottleneck is supply, not demand — the same message that separates winners from narrative casualties when AI stocks get indiscriminately sold.
The bubble talk, the trillion-dollar badge, and what still can break
Context matters. AMD first crossed a $1 trillion market-cap mark in September 2026 on a multi-day rally, CNBC reported at the time. [5] Reuters’ Wednesday wrap called it a recent trillion-dollar name, up about 126% year to date, and said a hold of the ~7.3% premarket move would add roughly $58 billion in market value. [4] CNBC, right after the earnings release, put the YTD gain near 125% (its key points said 129%) and noted three down days into the print on industry AI-spend fears. [2]
So yes — $AMD is priced like a franchise. Reuters notes a forward multiple near 31 times earnings versus about 14 times for Nvidia and 16.5 times for Broadcom. [4] Opinion: that premium only survives if Helios ramps, EPYC keeps taking share, and memory/packaging does not choke shipments. AMD also said PC unit shipments may fall by a double-digit percentage next year, even as Su expects to “outperform the market.” [3] Not a clean one-way tape — check the live chart and Finviz boards.
After Intel’s brutal week, a beat plus a raised AI trajectory is the pushback the category needed. More AI coverage: Artificial Intelligence / Super Intelligence.
What to watch next
- Helios volume in Q4. AMD says production continues to ramp and OEM/ODM partners begin shipping systems; Meta already said racks are up. Delivery vs. demo is the tell. [1][2]
- 2027 supply, not 2027 PowerPoints. Su’s wafer/substrate/packaging/memory lock-up claim has to show up in sequential Data Center dollars. [2]
- Gross margin math. Q4 non-GAAP GM guided to ~55% from 56% in Q3 — watch whether mix and HBM costs keep nibbling. [1][3]
- PC and Gaming drag. Double-digit PC unit declines would keep Client/Gaming noisy even if Data Center carries the narrative. [3]
- Competitive share vs. Nvidia. AMD is still the challenger in AI GPUs; Helios and ROCm have to convert design wins into durable attach, not tourist racks. [1][4]
The bottom line: AMD did not politely reassure the market — it buried a week of AI-spend panic under record Data Center dollars and a 2027 growth call that sits above consensus. Opinion: if you needed proof that AI CapEx still has a pulse outside one GPU vendor, Tuesday night was it. Execution risk remains enormous at these valuations.
This article is for information only and is not investment advice. Figures are from company releases and the reporting cited below as of November 4, 2026 (America/Chicago).
References
- AMD Reports Third Quarter 2026 Financial Results, Advanced Micro Devices, Inc. (IR press release), November 3, 2026.
- AMD stock jumps 8% on earnings as data center revenue nearly doubles, CNBC, November 3, 2026.
- AMD forecast eases AI spending fears as data-center sales surge, Reuters (via Investing.com), November 3, 2026.
- AMD shares jump as AI-driven data-center strength fuels growth outlook, Reuters (via Investing.com), November 4, 2026.
- AMD hits $1 trillion market cap for the first time as stock rides 5-day rally, CNBC, September 21, 2026.
Image credits
- Featured / header graphic: Base photo “2485 Augustine Drive headquarters in Santa Clara, California” by Coolcaesar, Wikimedia Commons, licensed CC BY-SA 4.0. Cropped, contrast-adjusted, and overlaid with typography/stats by if.finance; derivative shared under the same license.
- AMD logo: From amd.com via Wikimedia Commons (AMD Logo.svg), PD-textlogo. Trademark of Advanced Micro Devices, Inc., shown for identification only.
- Chart: Made by if.finance from AMD’s Q3 2026 earnings release. Linked to the IR source.
- Thumbnail (300×200): Same featured base, resized/cropped for archive cards; CC BY-SA 4.0 share-alike applies.