Micron ($MU) Gets Mugged by Kioxia’s Warning: Is Wall Street Dumping the Wrong Memory Stock?
Micron just posted the biggest quarter in its history, with $54.23 billion in revenue. On November 2 the market knocked $51.15 off the stock in a single session anyway. The trigger wasn’t Micron at all. It was a cautious outlook from Japanese flash maker Kioxia. Our take: traders lumped a DRAM-and-HBM powerhouse in with its NAND-heavy peers, and mid-December earnings are where that bet gets settled.

Micron Technology ($MU) has spent 2026 as one of the loudest public bets on AI memory. Then a rival blinked. Kioxia guided December-quarter operating profit only slightly above the prior quarter and below estimates, and U.S. memory names sold off in sympathy. Micron closed at $833.59, down 5.78% from an $884.74 prior close, according to Yahoo Finance. After-hours trading then bounced toward about $853. That bounce suggests at least some buyers thought the market had overreacted. [4][5]

Micron is one of the AI and Super Intelligence names on Grok’s October stock-picks list. Whether Monday hurt isn’t the question. It did. The real question is whether a NAND specialist’s soft guide tells you anything lasting about a company whose profit engine is DRAM and high-bandwidth memory (HBM). Our view: mostly no. The stock still has to prove it in December.
A record quarter the market seems to have forgotten
Start with the numbers from Micron’s own release. For the fiscal fourth quarter ended September 3, 2026, revenue was $54.23 billion, up from $41.46 billion the prior quarter and $11.32 billion a year earlier. GAAP net income was $37.70 billion, or $32.87 per diluted share. Non-GAAP EPS was $33.42. [1]
For the full fiscal year, revenue reached $133.19 billion, up from $37.38 billion. Non-GAAP net income was $86.76 billion. Cash, marketable investments and restricted cash ended the year at $73.48 billion, and adjusted free cash flow was $62.31 billion for the year after $27.37 billion of net capital spending. [1]
CNBC, citing LSEG, said the $33.42 adjusted EPS beat a $31.61 consensus and revenue beat a $51.07 billion estimate. Then management raised the bar. Micron guided fiscal Q1 2027 revenue to $61.5 billion ± $1.5 billion, with non-GAAP gross margin of about 86.25% and EPS of $38.15 ± $1.00. That compares with the roughly $57 billion and $35.40 LSEG expectations CNBC cited. [1][2]
CEO Sanjay Mehrotra didn’t sound like someone bracing for a downturn: “AI is becoming Super Intelligence (SI), and memory enhances this intelligence and the competitiveness of our customers’ platforms… our Strategic Customer Agreements provide added confidence in the durability of Micron’s financial performance.” [1]
Our take: a company guiding the next quarter about $4.5 billion above consensus is planting a flag. A one-day selloff driven by somebody else’s guidance doesn’t erase that.
Kioxia sneezed. Does Micron really catch the cold?
Kioxia’s November 2 update was the spark. 24/7 Wall St. reported that Kioxia guided December-quarter operating profit to ¥2 trillion, barely above about ¥1.99 trillion in the September quarter and below estimates. CFO Yoshihiko Kawamura called it shipment timing, with some orders pulled into September and others pushed into March. He also said AI data-center demand stays robust, that next year’s planned output is already sold out, and that rapid growth should return in the March quarter. [4]
Read that again: even the company that triggered the selloff called it a timing issue, not a demand problem. Western Digital and SanDisk, which are far more tied to flash, fell about 5% and 3% intraday in the 24/7 account. That makes sense. Micron is a different animal. Its prepared remarks put fiscal Q4 DRAM revenue at a record $39.8 billion, up 343% year over year and 73% of total sales. NAND was $14.1 billion, about 26%. [3][4]
HBM sits inside that DRAM engine. CNBC noted that Micron is the only U.S.-based HBM maker and is working with Nvidia on a custom HBM implementation. The prepared remarks say HBM revenue grew faster than total revenue in Q4 and that the vast majority of calendar 2027 HBM bit supply is already agreed, with significant year-over-year price increases. They add that Micron is ramping HBM4 while collaborating with NVIDIA on NVHBM (custom HBM4E). [2][3]
Business-unit sales show where the money went. Core Data Center brought in $18.002 billion, Cloud Memory $16.283 billion, Mobile and Client $13.114 billion, and Automotive and Embedded $6.824 billion. [1]
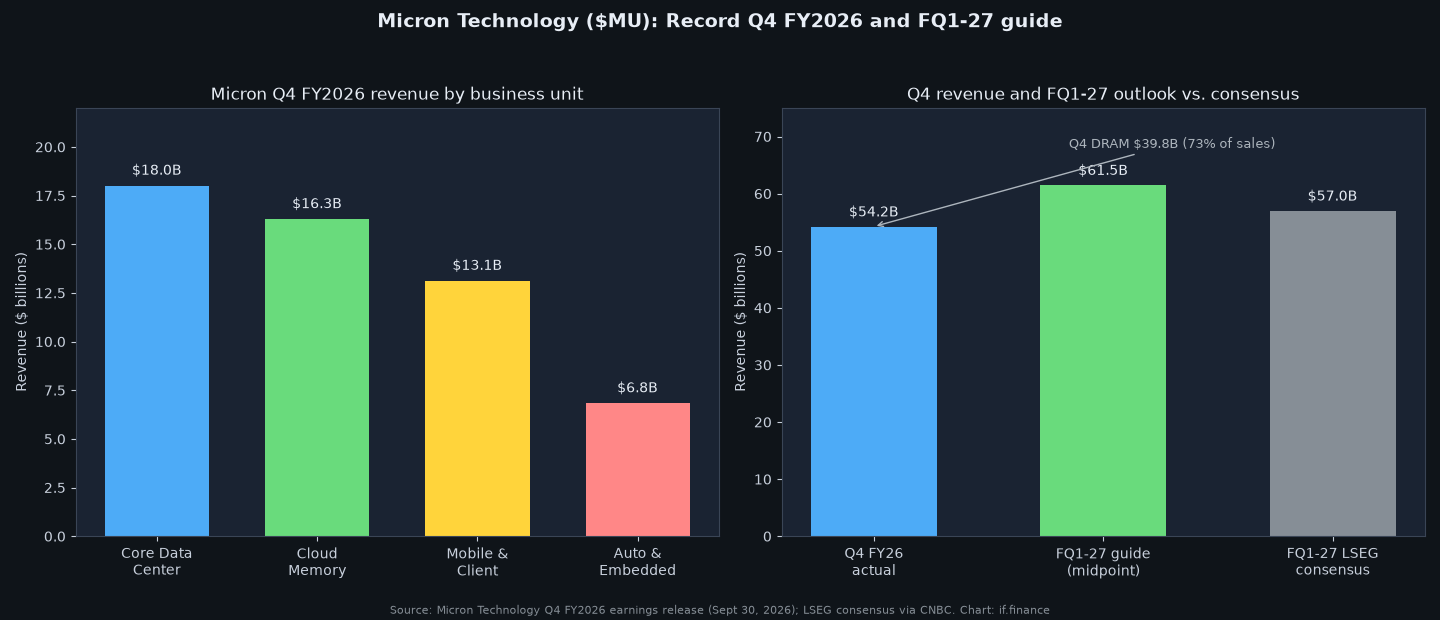
Our take: selling a 73%-DRAM company because a flash maker shifted shipments between quarters looks like reflex, not analysis. That doesn’t make the drop irrational. It means the market is trading the memory group rather than the business mix.
The bull case: scarcity, contracts and cash
Management’s pitch is scarcity, not a soft landing. According to 24/7 Wall St.’s recap of the September 30 earnings call, President and COO Manish Bhatia said Micron does not have “line of sight to when supply and demand balance,” and more than 75% of shipments were already committed for the year. [4]
The prepared remarks back that up with contracts. Micron has 26 strategic customer agreements, estimated at more than 35% of revenue through 2030. Remaining performance obligations are about $150 billion on contracts with set pricing frameworks, and customer financial commitments total $32 billion, mostly cash deposits. [3] Customers don’t usually wire deposits for a product they expect to be cheap next year.
The bear case you can’t wave away
Here’s the tension. Monday’s drop didn’t start from a calm base. 24/7 Wall St. put $MU roughly 20% lower over the prior month even after the record print. Yahoo Finance’s one-month figure around the November 2 close was about −22%, while the year-to-date return was still about +192%. [4][5] You can track the live tape on our chart page.
A stock that has nearly tripled this year doesn’t need a disaster to fall. It just needs doubt. If AI memory pricing rolls over, or hyperscalers stretch out HBM and high-capacity DRAM purchases, a name priced for scarcity can reprice fast. Yahoo Finance showed an average analyst price target near $1,562 as of the November 2 quote page. That is a very bullish Street view, and it assumes the cycle holds. [5] Capex is another swing factor: CNBC reported about $250 billion for Micron’s planned U.S. campuses in Clay, New York, and Boise. [2]
Our take: the bears aren’t wrong that memory is cyclical. They are early to assume this cycle ends on a competitor’s shipment timing.
What to watch next
- Mid-December earnings. Fiscal Q1 2027 results are expected in mid-December. Micron hasn’t confirmed the date on its IR site yet. Delivering on the $61.5 billion ± $1.5 billion guide is the whole ballgame. [1]
- DRAM vs. NAND pricing. Kioxia’s commentary is a NAND signal. Watch whether Micron’s DRAM and HBM pricing keeps climbing. [3][4]
- HBM4 / NVHBM execution. Watch for confirmation that calendar 2027 HBM supply stays contracted and that the Nvidia custom path stays on track. [3]
- Capex and U.S. fabs. Watch delivery timelines on the U.S. campus builds (about $250 billion for Clay and Boise, per CNBC). [2]
- More AI memory coverage in our AI and Super Intelligence section.
The bottom line (opinion): Wall Street just sold Micron for a rival’s timing problem. If the December print lands near guidance, Monday will look like a gift. If it doesn’t, the bears will have been early rather than wrong. Either way, the fight is over Micron’s own numbers, not Kioxia’s.
This article is for information only and is not investment advice. Sections marked “Our take,” “Our view” or “opinion” are if.finance analysis and opinion. Figures are from company filings and the reporting cited below as of November 3, 2026.
References
- Micron Technology, Inc. Reports Record Fiscal Fourth-Quarter and Full-Year 2026 Results, Micron Technology, Inc. (press release / GlobeNewswire), September 30, 2026.
- Micron beats on earnings and issues strong guidance as data center revenue jumps 11-fold, CNBC (Katie Tarasov, Kif Leswing), September 30, 2026 (updated October 1, 2026).
- Q4 FY26 Prepared Remarks, Micron Technology, Inc., September 30, 2026.
- Micron Falls 4% as Kioxia’s Cautious Outlook Hits Memory Stocks; Western Digital Drops 5%, SanDisk Slides 3%, 24/7 Wall St. (David Moadel), November 2, 2026.
- Micron Technology, Inc. (MU) quote and performance, Yahoo Finance, as of close November 2, 2026.
Image credits
- Featured graphic: made by if.finance using “Micron Fab in Taichung, Taiwan” by Thingreenline4546 (Wikimedia Commons, CC BY-SA 4.0). The photo was cropped and darkened, with text and figures added; the graphic is shared under CC BY-SA 4.0. The figures come from the Yahoo Finance quote and Micron’s Q4 FY2026 release.
- Featured photo (in article): “Micron Fab in Taichung, Taiwan” by Thingreenline4546, Wikimedia Commons, licensed CC BY-SA 4.0. Cropped to 1200×628 by if.finance.
- Micron logo: from Micron’s press image gallery via Wikimedia Commons (PD-textlogo). Trademark of Micron Technology, Inc., shown for identification only.
- Chart: made by if.finance from Micron’s Q4 FY2026 earnings release and LSEG consensus as reported by CNBC.